
OneMain Financial
- Rating
- 4.7
- Downloads
- 1.00M
- Content Rating
- Everyone
OneMain Financial - Screenshots
Pros
- Prequalification uses a soft credit check that typically does not affect your score.
- Loan funds may arrive quickly after approval and final verification.
- Fixed-rate payments make monthly budgeting more predictable.
- Joint applications can help some borrowers qualify or access better terms.
- Online account tools make payments and loan management convenient.
Cons
- APR ranges can be high
- especially for borrowers with weaker credit.
- Origination fees may reduce the amount you actually receive.
- Loan availability and terms vary by state and applicant profile.
- Late or missed payments can lead to fees and credit score damage.
- A secured loan may require collateral
- such as a vehicle.
OneMain Financial - Description
- App Name
- OneMain Financial
- Package Name
- com.springleaf.mobile
- Developer
- OneMain Financial
- Category
- Finance
- Last Updated
- Apr 10, 2014
- Version
- 10.31.0
Managing a personal loan from a phone sounds simple until a payment date gets close, a balance needs checking, or a credit question appears at an inconvenient moment. I spent time looking at how OneMain Financial fits into those ordinary situations, and my impression is that it is most useful when you already have a loan with OneMain and want a direct way to keep an eye on it. This is a finance app from OneMain Financial, offered free of charge and rated for Everyone.
The app has a clear purpose rather than trying to become a general-purpose banking replacement. Its focus is loan management, payments, and credit tracking. That narrow scope is actually one of its strengths: I do not have to dig through unrelated budgeting tools or shopping features to reach the information that matters to a borrower. At the same time, that focus also defines who should use it. If you do not have a OneMain loan, or if you want a complete view of several banks, cards, investments, and household accounts in one place, this is probably not the right first choice.
How OneMain Financial handles everyday loan management
The useful moments depend on a live connection
The most important thing to understand is that this is a connected account-management experience. Checking loan information, making a payment, and viewing credit-related details are activities where the app needs to communicate with OneMain’s systems. I would not treat it like a document saved on the phone or a calculator that remains fully useful without a network connection. When the connection is available, the experience is centered on getting current account information and sending actions to the lender.
That matters most around payment time. Imagine I am leaving work, remember that a payment needs attention, and open the app from my phone. The value is not simply seeing a screen with a loan name on it. I want the current amount, the relevant account details, and a clear path to complete the payment. A connected app can reduce the number of steps compared with searching through old emails, calling support, or opening a desktop browser. The trade-off is that a weak signal can turn a quick task into a waiting exercise.
I also see a practical difference between browsing and committing an action. Looking at a balance is one kind of task; submitting a payment is more sensitive. A delayed screen or interrupted connection can make a user wonder whether the request went through. My advice is to avoid tapping repeatedly when a payment screen appears slow. First check whether the app has updated, look for a confirmation or changed account status, and then verify through the account history before trying again. That habit is more important here than it would be in a casual app because duplicate payment attempts can create unnecessary confusion.
The app’s 4.7 average from around 28 thousand ratings suggests that many users find this focused approach useful. I would read that as a sign of a generally positive day-to-day experience, not as a promise that every payment or connection will be effortless. Finance apps are judged in stressful moments, and even a small delay feels larger when money is involved.
What it feels like in mobile contexts
OneMain Financial makes the most sense for people who manage their loan away from a desk. A phone is usually nearby when I am commuting, handling errands, or reviewing the month’s bills. That convenience can be meaningful for someone who does not want to wait until they are at a computer to confirm a payment or check where an account stands.
The interface is best approached as a task tool. I would open it with a specific reason: review the loan, make a payment, or inspect credit information. That mindset keeps the experience efficient. It is less suited to long financial planning sessions, where a larger screen, a spreadsheet, or a broader budgeting service may make comparisons easier. The app can help me stay connected to one lender, but it does not replace the thinking required to decide whether a payment fits my wider budget.
A useful mobile routine is to check the account before the payment date rather than waiting until the last possible moment. Doing so gives me time to deal with a poor connection, an unexpected sign-in issue, or a payment detail that needs a closer look. I would also avoid doing the final step while rushing through a crowded station or switching constantly between apps. A loan payment deserves enough attention to confirm the amount and completion status.
Another realistic use is a quick mid-month check. If I am trying to understand how a recent payment affected the account, opening the app can be more convenient than reconstructing the answer from bank transactions alone. The important distinction is that a bank statement tells me money left one account, while the lender’s own view is the more relevant place to check how the loan account reflects that activity.
Credit tracking is helpful, but it needs context
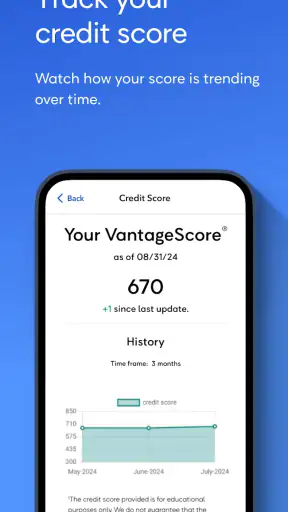
The credit-tracking side gives the app a broader role than a simple payment button. I like the idea of having loan management and credit awareness in the same place because borrowers often want to understand more than the next due amount. Seeing credit-related information can encourage better habits, especially when someone is trying to monitor progress rather than ignore the account between payments.
Still, I would not use a credit view as the only basis for a major financial decision. Credit information is useful context, but it is not the same thing as a complete personal-finance plan. A user deciding whether to apply for another loan, change a budget, or close an account should consider income, existing obligations, and the terms of the decision rather than relying on one screen. The app is strongest as a convenient checkpoint, not as a substitute for careful financial judgment.
One practical tip is to compare what the app shows with the purpose of your visit. If I am checking credit information, I would write down the question I am trying to answer before opening the app: am I monitoring a change, looking for a general snapshot, or reviewing how my borrowing fits into a larger plan? That prevents me from treating a single number as a complete explanation.
Where it differs from ordinary alternatives
The usual alternatives fall into two groups. The first is using a mobile browser to sign in to the lender’s website. A browser can be perfectly adequate, especially for someone who rarely checks the account or prefers not to install a dedicated app. The advantage of OneMain Financial is convenience: the lender’s mobile experience is kept in one place, so a recurring task can feel less cumbersome than navigating a website each time.
The second group is general finance apps that gather information from several institutions. Those services are better when my main need is a complete household overview, such as comparing a OneMain loan with credit cards, checking accounts, and savings. Their weakness is that a broad dashboard may not feel as direct for a lender-specific action. OneMain Financial has the opposite trade-off: it is more focused, but less useful as an all-in-one financial command center.
I would choose the dedicated app if I already have a OneMain account and frequently need lender-specific access from my phone. I would lean toward a browser if I want to minimize installed apps or only need occasional access. I would choose a broader finance tool if my real problem is seeing every account together. None of those choices is universally better; the right one depends on whether convenience, breadth, or simplicity matters most.
What happens when connectivity or a session fails
Connectivity problems are the main friction point I would plan around. A basement, elevator, rural road, crowded event, or overloaded public network can make a connected finance task unreliable at exactly the wrong time. I would not wait until the final minutes before a payment deadline if I know my signal is unpredictable. Opening the app earlier gives me a chance to complete the task while the connection is stable.
If a screen does not load, I would start with the basics: move to a stronger signal, close and reopen the app, and sign in again only if necessary. I would avoid repeatedly submitting a payment simply because the response is slow. The safest recovery workflow is to confirm the account status and transaction history first. If the app still does not give a clear result, I would use OneMain’s available support route rather than guessing.
There is also a difference between an app failure and a bank-account issue. A payment may require attention from both the lender side and the funding account side, so a successful-looking step in one place should not encourage me to ignore the other. I would keep the relevant bank record available until the transaction is clearly reflected. That is a small but valuable discipline when using any connected loan service.
Updates can affect this recovery process as well. The current version is 10.31.0, and the app supports Android 7.0 or later. I would keep the application updated when possible, but I would avoid installing an update for the first time moments before an important payment. Updating earlier, while I have a stable connection and time to sign in again, is the less stressful approach.
Using it without wasting mobile data
Because the app is designed around account information and connected actions, I would use it deliberately rather than leaving it open in the background. For most borrowers, the sensible pattern is to open it when needed, complete the task, confirm the result, and close it. That keeps the app’s role clear and avoids treating a finance dashboard like a social feed that needs constant refreshing.
On a limited mobile plan, I would reserve payment and detailed account checks for a trusted Wi-Fi connection when that is convenient, while remembering that public networks deserve caution. I would not enter sensitive financial information on an unfamiliar network simply to save a small amount of cellular data. Security and correctness matter more than avoiding every megabyte.
Another data-conscious habit is to avoid refreshing repeatedly when information appears unchanged. If I have just checked the account and no new event has occurred, reopening the same screen several times is unlikely to improve my understanding. I would instead note what I need to verify and return later. This is especially useful when traveling, where connectivity may be expensive or inconsistent.
I also recommend keeping notifications and account reminders purposeful rather than reacting to every possible prompt. The goal is to remember a payment or review an account, not to create more noise. A simple calendar reminder paired with a deliberate app check can be more useful than opening the service repeatedly throughout the day.
Who will get the most from it
This app is a good fit for an existing OneMain borrower who wants a convenient mobile route to loan information and payments. It is also useful for someone who is trying to build a regular review habit. Instead of treating the loan as something to think about only when a notice arrives, I can use the app as a quick checkpoint before and after payments.
It may suit users who are comfortable doing routine financial tasks on a phone and who value a lender-specific experience over a broad money-management dashboard. The free price removes an obvious barrier to trying it, and its Everyone age rating makes the basic audience broad. OneMain Financial has more than a million installs, which also shows that the mobile approach is familiar to a substantial user base.
I would skip it if I do not have a OneMain relationship, if I mainly need investment tracking, or if my priority is combining many financial institutions in one detailed budget. I would also think twice if I dislike handling sensitive account tasks on a phone or regularly work in places with unreliable connectivity. In those cases, a browser, direct support channel, or wider financial tool may fit better.
My connectivity verdict
My overall view is positive, with a clear boundary: OneMain Financial is valuable because it keeps lender-specific tasks close at hand, but that convenience depends on a working connection and careful confirmation. I would recommend it to a OneMain borrower who wants to check a loan, make payments, and keep an eye on credit information without reaching for a computer every time.
The best way to use it is not to wait for a stressful deadline. Check the account early, use a stable connection, review the payment details before submitting, and verify the result afterward. If a screen hangs, do not assume failure or success; confirm the account status before trying again. Those habits make the connected nature of the app much less troublesome.
In the end, I see it as a focused companion rather than a complete financial planner. It will not replace a household budget, a multi-bank dashboard, or thoughtful borrowing decisions. What it does offer is a direct mobile relationship with OneMain Financial, and for the right borrower, that focused access is exactly the point. With a 4.7 average and around 3.3 thousand written reviews, its reception is encouraging, while the practical limitations are straightforward enough to manage.
My recommendation: install it if you already use OneMain Financial and want a simpler way to stay involved with your loan from a phone. Keep a browser or support option in mind for unusual problems, and never let a slow connection push you into submitting the same payment twice.
FAQ
What is OneMain Financial, and what services does it offer?
OneMain Financial is a lending and financial-services app that allows eligible users to explore personal-loan options, review account information, make payments, and manage loan-related tasks from a mobile device. Depending on your location and eligibility, the service may provide secured or unsecured personal loans. Available amounts, rates, terms, and features can vary, so review the official offer carefully before accepting anything.
Can I apply for a personal loan through the OneMain Financial app?
The app may let you begin or continue a personal-loan application, although some applicants may be directed to the company’s website or asked to complete additional steps with a representative. Approval is not guaranteed, and eligibility can depend on factors such as income, credit history, requested amount, and state requirements. Carefully check the annual percentage rate, fees, repayment term, and total cost.
Is OneMain Financial safe to use on Android or iPhone?
OneMain Financial uses standard security measures intended to protect account information and communications, but no online financial service can eliminate every risk. Download the app only from the official Google Play Store or Apple App Store, verify the developer name, keep your operating system updated, and avoid entering credentials on public or suspicious networks. Enable device security and contact support if unusual activity appears.
What can I do inside the OneMain Financial mobile app?
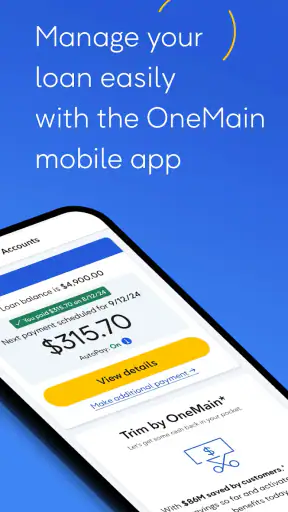
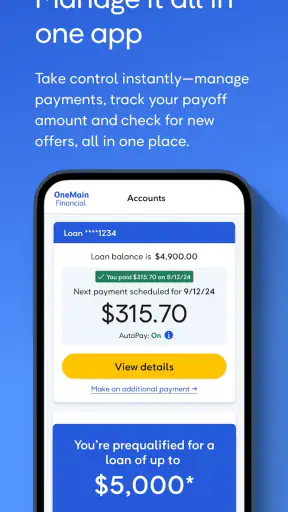
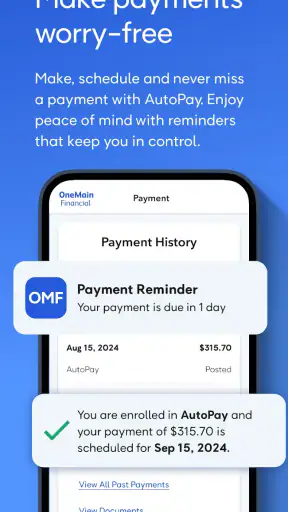
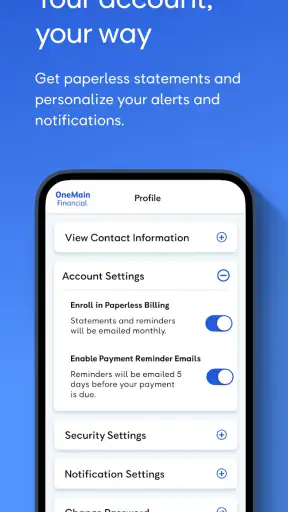
After signing in, users can generally view loan balances, check payment details, review transaction or account information, make one-time payments, and manage certain personal settings. Exact features may differ based on your account, loan type, and app version. Before relying on the app for a deadline-sensitive payment, confirm that the transaction was successfully submitted and keep any confirmation information for your records.
Are there fees, credit checks, or risks I should know about before using OneMain Financial?
Using the app itself may not be the same as accepting a loan, but applying or receiving an offer can involve credit review, eligibility checks, interest charges, and possible origination or other fees. Loan costs vary by applicant and location, and late or missed payments may lead to additional charges or affect your credit history. Read all disclosures and repayment terms before agreeing.


